
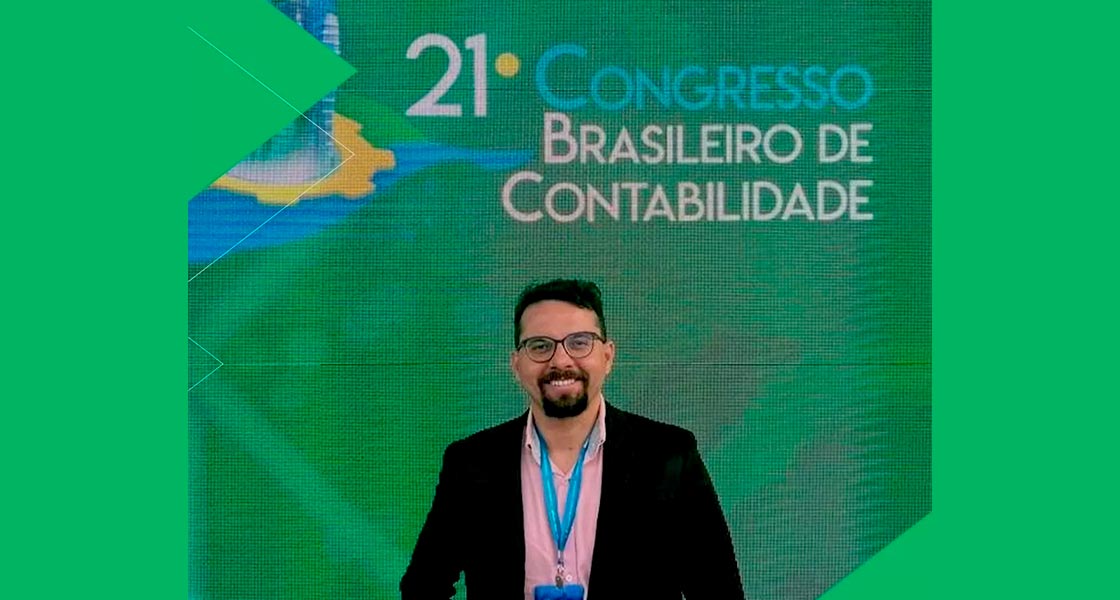
Our Tax Coordinator, Victor Magalhães, attended the 21st Brazilian Congress on Accounting held in Balneário Camboriú, where specialists discussed topics crucial to the future of accounting in Brazil.
Among the main points discussed, new international standards such as IFRS S1 and S2, the digital transformation of the sector and the impacts of the ongoing tax reform stood out.
In the field of accounting standards, discussions emphasized the importance of updates aimed at standardizing and increasing transparency in global corporate practices. IFRS S1 and S2, for example, introduce innovations related to sustainability. IFRS S1 requires the disclosure of information on governance, strategies and risks associated with companies’ sustainable performance, while IFRS S2 focuses on climate impacts, covering greenhouse gas emissions and climate-related financial risks.
Additionally, the replacement of IAS 1 by IFRS 18, as discussed, promises to improve the presentation of financial statements. Among the highlights of the new standard is the creation of specific categories for revenues and expenses, facilitating comparability between companies. The standard also requires detailed disclosure of Management Performance Measures (MPMs) defined by management, contributing to greater clarity and confidence in the information provided to the market.
Another point of attention was the digital transformation of accounting, a trend aimed at modernizing processes through new technologies. This transformation encompasses the digitalization of documents, the automation of repetitive tasks and the adoption of cloud technologies. According to Victor, “digitalization brings benefits such as increased productivity, greater operational efficiency and cost reduction, allowing accounting professionals to take on a more consultative and strategic role.”
This transformation, however, demands a mindset shift from accountants, who must invest in new tools, seek continuous learning and concentrate their efforts on strategic advisory. The idea is that, with the support of new technologies, the accountant’s role will come to encompass management analyses, tax planning and broader business strategies.
The tax reform, one of the most widely debated topics during the congress, was also addressed comprehensively. According to Magalhães, “the proposal aims to modernize and simplify the tax system, dividing its implementation into three phases of administration.” Tax Administration 1.0 is characterized by manual processes and intensive use of paper, 2.0 includes digitalization and the use of analytical tools, and 3.0 focuses on the integration of tax rules into accounting systems, with digital audits and real-time taxation.
During the event, the Split Payment mechanism, part of the reform, was highlighted as a relevant innovation for simplifying tax collection. In this system, payment for a transaction would be automatically split between the supplier and the tax authority, which would reduce bureaucracy and increase transparency in the tax collection process. In terms of ancillary obligations, government representatives indicated that APIs (application programming interfaces) are being developed for use by taxpayers, enabling the integration of tax software with automatic transmission of information to the tax authorities.
At the event, the advantages of the tax reform were highlighted, considering simplification through the unification of taxes into a VAT, and the reduction of bureaucracy by decreasing ancillary obligations and promoting greater transparency. Other points highlighted include the end of the fiscal war between states and greater efficiency in resolving tax disputes through an integrated administrative dispute resolution mechanism.
On the other hand, criticism focused on the possibility of an increase in the tax burden, given that the VAT rate may become one of the highest in the world. The lengthy transition period planned through to 2033, which may create legal uncertainty, was also discussed, along with the exceptions and benefits that could raise the general rate. There are also concerns about the impact on employment and potential federal conflicts, due to the redistribution of tax competencies between states and municipalities.
The congress therefore reinforced the need for taxpayers to make adaptations and investments, particularly in integrated tax management systems and automated monitoring tools. Magalhães points out that “the reform will require the implementation of technologies such as integration APIs and compliance modules, in order to guarantee secure and real-time data transmission.”
In summary, the 21st Brazilian Congress on Accounting brought to light the urgency of adaptations in the face of a scenario of constant regulatory, technological and fiscal changes. Amid more robust international standards, the digitalization of accounting processes and the new guidelines of the tax reform, the event highlighted a future in which transparency and efficiency must guide Brazilian accounting.